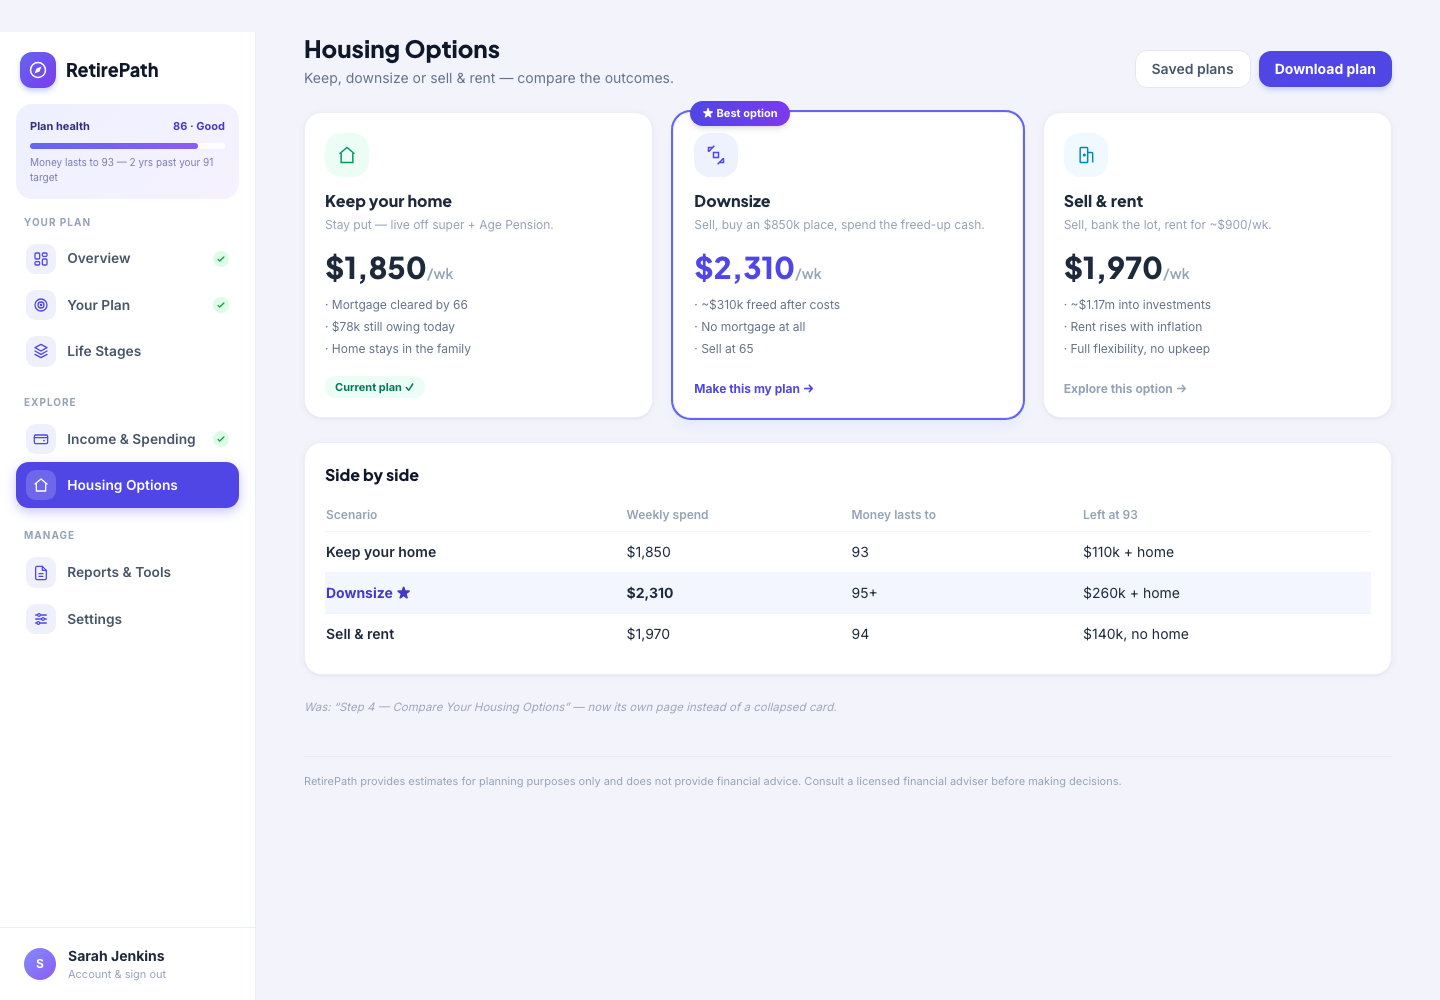
For most Australians, the house is the retirement fund. RetirePath prices the three real options — keep, downsize, or sell and rent — on your actual figures, side by side.
Stay in the family home. The model accounts for the mortgage (if any), upkeep, and the fact that the house isn't spendable — equity isn't groceries.
Sell, buy smaller, free the difference. Transaction costs, the new home's price and the freed capital all flow into the projection.
Sell up entirely and invest the lot, with rent as an ongoing cost — the option people dismiss without ever seeing the numbers.
Each scenario shows the max weekly spend it supports and the age money lasts to. Sometimes keeping wins; sometimes renting does. Now you'll know.
Every scenario runs the identical engine on the same base numbers — the only difference is the housing choice, so the comparison is fair.
Stamp duty, agent fees, moving — the costs people forget when they imagine downsizing are all in the model.
Still paying the house off into retirement? The projection carries the repayments until it's done.
Home equity and invested cash are treated differently by the Age Pension means test — the scenarios reflect that.
Downsize at 60 or at 75? The age you sell changes the answer, and it's a slider, not a rebuild.
Scenarios aren't a separate calculator — they feed the same weekly-spend and lasts-to-age numbers as everything else.
Put in your home value and see all three futures — free to try.
Start your free trialQuestions first? Talk to us