Our story
I'm not a software developer by trade — my background is business development and management. But in my role, I ended up building software — systems that run registrations, payments and members. Real software, used by real people every week. So when I hit a problem software could solve, I knew how to solve it.
The major hurdle in today's world is knowing what we will have left when we retire. RetirePath started because I didn't understand my own retirement. I'm in my fifties, and I honestly didn't know what I'd actually have at 60 — not the super balance on the annual statement, but what it meant for my life. Could I stop working? What could we spend each week? What does life look like between 60 and the Age Pension at 67, and what happens after that? The years had no shape to them — it was all just "retirement, some day."
And when I started asking around, it turned out most of my friends were even more confused than I was. A surprising number genuinely believed you couldn't touch your super until 67 — they didn't realise your own money unlocks at 60 (provided you meet a condition of release, like retiring or starting a transition-to-retirement strategy), and that the government's pension is a completely separate thing. Some didn't know what they could draw while still working, or that they could clear the mortgage from super, or that super and the Age Pension play by totally different rules. These are smart, organised people — and the biggest financial transition of their lives was a mystery to them.
The options for figuring it out were grim. A one-off adviser report: expensive, out of date within a year, and impossible to tinker with. Spreadsheets: fragile, and only as good as the person who built them. Online calculators: fine for a single number, useless for the real questions — what if I sell the house? What if I stop at 60? What if we spend more in the good years?
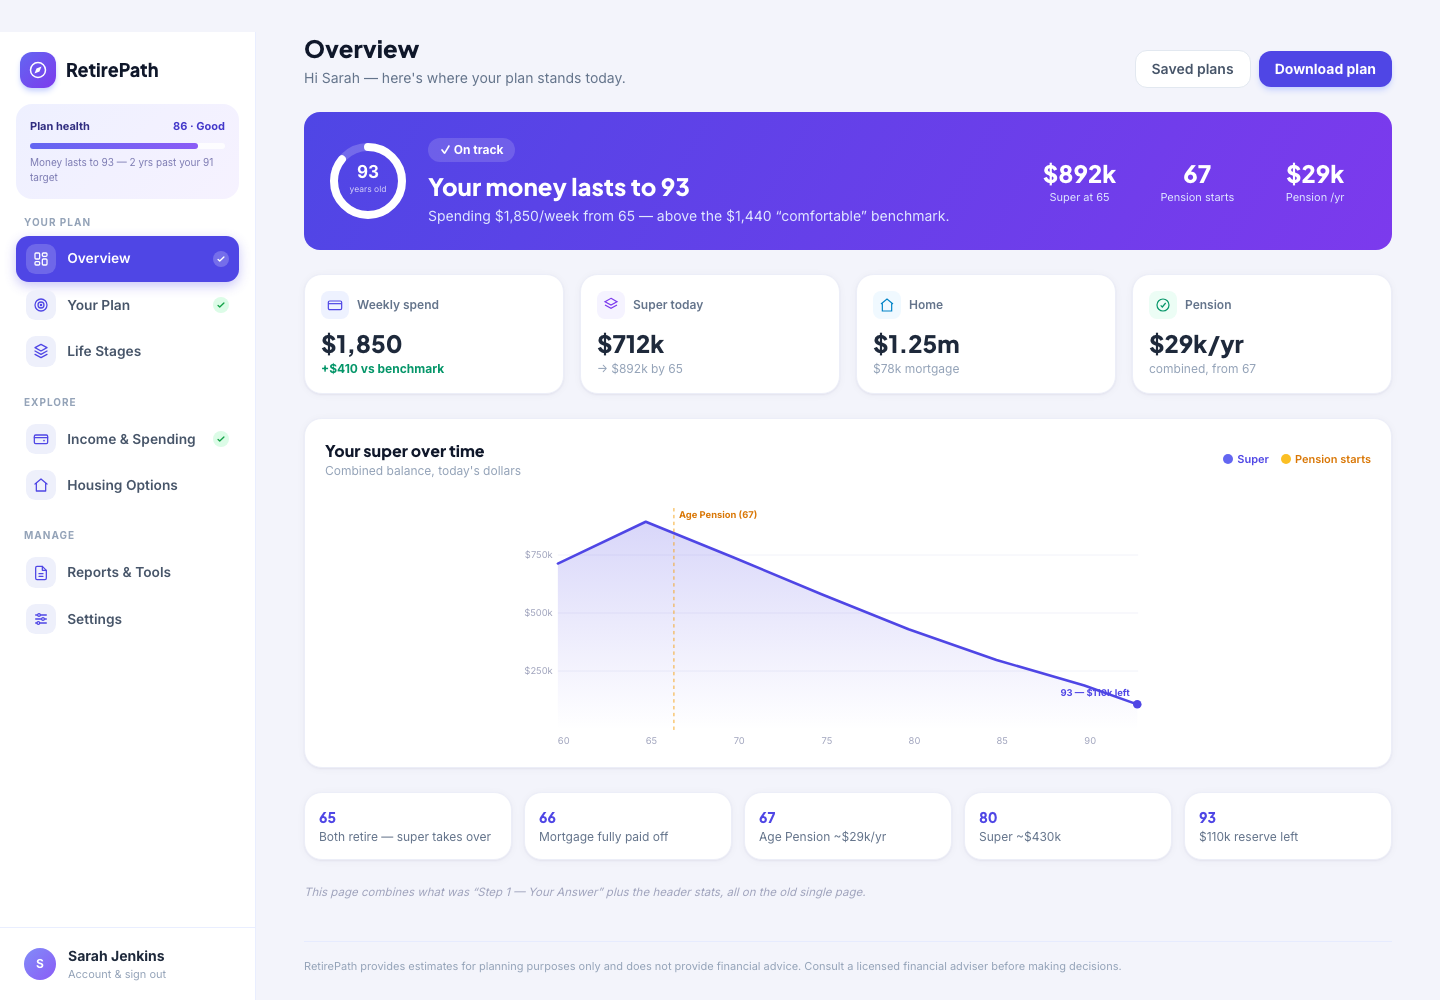
So I built the tool I wanted: a live model of your own retirement that splits your life into understandable stages — still working, the early freedom years, super kicking in at 60, the pension joining at 67 — and shows what each one looks like in dollars. Income, spending, housing, pensions — year by year, with every assumption visible. It explains the rules in plain English as it goes, because half the battle is just knowing what you're allowed to do.
It's a guide — and it can always be checked by an adviser if you need one. But it could save you thousands in costs before you ever get to that step.
And it's a subscription on purpose, because the question doesn't get asked once. It gets asked every time life changes — and every time the government changes the rules, which happens more often than you'd think.
"I built RetirePath because I couldn't answer my own question — and it turned out none of my friends could either. Once you see your retirement in stages, it stops being a mystery."
— Stu, Founder of RetirePath
Ten minutes of setup, then your answer — free to try.
Start your 7-day free trialQuestions first? Talk to us
